Almost everyone who has banked in the UAE has a fall-below fee story. You start a new job, open an account in a rush, and a couple of months later a small deduction turns up on the statement. Nobody warned you. The balance sat under the limit for a few days before payday, and the bank did exactly what its schedule of charges allowed.
A no minimum balance account takes that worry away. Whatever you hold in it, whether that is AED 40 or AED 40,000, the bank does not penalise you for the gap. The catch is that the phrase gets used very loosely. Some accounts really are zero balance with no strings. Others are zero balance only if your salary lands there every month. A few skip the balance rule but charge a monthly plan fee instead.
This guide separates those three types, compares the accounts residents actually use, and points you to the one that fits your situation. It works whether you have just landed in Dubai, freelance from a coffee shop in Al Quoz, sit on a fixed salary in Abu Dhabi, or simply want a spot to park savings without paperwork.
What a No Minimum Balance Account Really Means
Banks set a minimum balance to cover the cost of running an account. Wikipedia’s page on the minimum daily balance explains the general idea: fall below the required amount and the bank can charge a maintenance fee. In the UAE the rule is usually measured as a monthly average rather than a daily figure, and the typical personal current account has asked for AED 3,000 or AED 5,000.
When a bank says an account has no minimum balance, it can mean one of three quite different things:
- Truly zero balance. No minimum to open, no minimum to keep, no salary needed. ruya Community Islamic Bank is the clearest example, and its own page says exactly that.
- Conditional zero balance. The minimum disappears only when you meet a condition, usually a salary transfer. Emirates Islamic works this way. Some banks accept alternatives such as a credit card, regular spending or a modest average balance.
- Zero balance with a plan fee. The account stays open at any balance, but a monthly subscription applies unless you keep enough money in your Wio accounts, for example. It is not a fall-below fee by name, yet you still pay it.
Knowing which type you are looking at saves money. Two accounts can both carry a “no minimum balance” label and behave very differently in month three.
Why This Matters More Than It Looks
Take the fee that many banks charge when you drop below the line. It is commonly around AED 25 a month. That sounds small until you multiply it. Twelve months is AED 300. Five years is AED 1,500, paid for the privilege of having less money than the bank preferred.
Certain people feel this more than others. New arrivals often wait weeks for a first salary, and the Wage Protection System means employers pay into a bank account, so the account has to exist before the money does. Freelancers see income arrive in lumps. Students and part-time workers may never hold a large balance at all. For all of them, a rule that punishes a low balance works against the way they earn.
If you want a wider view of what the big traditional banks ask for in salary and balance, our guide to the best banks in Dubai for expats lays out the thresholds side by side. This article stays focused on accounts that ask for less.
No Minimum Balance Accounts in the UAE at a Glance
The table below sums up the accounts covered in this guide. Conditions come from each bank’s own pages and key facts statements where available, and from comparison sites where they are not. Where sources disagree, the table says so.
| Account | Type | What keeps the minimum balance fee away | Suits |
| ruya Personal Current Account | Current, Islamic, digital | Nothing. No minimum deposit to open, no minimum balance, no salary needed | Anyone who wants a simple account with no conditions |
| HSBC Flexi Account | Current | Reported as having no salary or balance condition. Confirm with the bank | Residents who like an international bank |
| Mashreq NEO Current Account | Current, digital | Salary of AED 5,000 or more, or a monthly average balance of AED 3,000 | Salaried people who live in their banking app |
| Wio Personal | Current, digital | No minimum balance. Standard plan adds AED 25 a month unless your average balance across Wio reaches AED 3,000 | Mobile-first users who want savings tools |
| Emirates NBD Liv | Current, digital | Reported: no salary needed, with spend, a credit card or a balance as alternatives | Younger professionals |
| Emirates Islamic Current Account | Current, Islamic | Salary transfer of AED 5,000 or more. Otherwise AED 3,000 minimum | Salaried customers who want Islamic banking |
| Al Hilal Bank Current Account | Current, Islamic, digital | Sources differ. Check the key facts statement | Islamic banking customers |
| SIB Digital Account | Savings-based, Islamic | Marketed as zero balance. One listing mentions a salary of AED 5,000 | App-first Islamic banking |
| FAB iSave | Savings | No minimum balance and no limit on withdrawals | Parking savings |
| Wio Business Essential | Business | No minimum balance. Monthly subscription applies | Freelancers and small companies |
Bank terms change without much noise. Treat this table as a starting point and confirm on the bank’s own page before you apply.
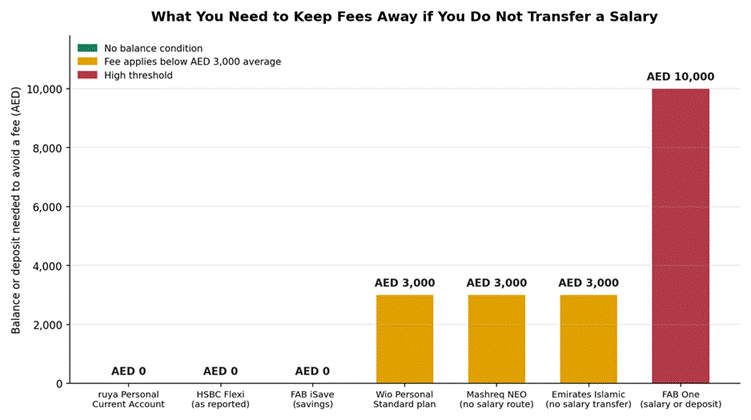
Balance or deposit needed to avoid a fee when no salary is transferred. Figures from bank pages and comparison sites, subject to change.
The chart tells a simple story. Without a salary transfer, three accounts on the list ask for nothing at all, three ask for around AED 3,000 held as an average, and one asks for a much larger sum. That gap is the reason it pays to read the conditions, not just the headline.
The Accounts in Detail
ruya Community Islamic Bank: the cleanest zero balance option
ruya is the easiest example to explain. The bank states on its current account page that no minimum deposit is needed to open an account and that you are not required to keep a minimum balance. It also says many of its accounts carry no salary requirement and no hidden fees, and that you can open one in about five minutes with UAE PASS or an Emirates ID.
It is Shariah-compliant, which matters to a lot of residents. As a newer digital bank it has fewer branches and cash machines than the older names, so if you deal in cash every day, plan around that. If you mostly pay by card and app, you will barely notice.
Mashreq NEO: great app, but read the condition
NEO is Mashreq’s branchless digital brand. Its key facts statement says you avoid the fall-below fee by crediting a monthly salary of at least AED 5,000 or by keeping a monthly average balance of AED 3,000. Miss both and the fee applies. So it is not a pure zero balance account, even though some summaries online describe it as one.
For salaried residents this is a comfortable fit. The application runs entirely in the app, and the bank regularly runs salary cashback offers on the NEO current account page. Those offers change, so check the current terms before you count on them.
Wio Personal and Wio Business: no minimum, but plans have fees
Wio’s key facts statement says no minimum balance is required to maintain a personal account. The plan structure is where the money question sits. On the Standard plan a monthly fee of AED 25 applies if your average balance across Wio accounts stays under AED 3,000. The Plus plan asks for AED 35,000 before its AED 49 fee is waived.
In other words, the account stays open and usable at any balance, but you may pay a subscription. Whether that counts as “no minimum balance” depends on how strictly you read it. One more detail from the same document: Wio may block or close an account that stays at zero with no activity, or below the minimum, for 90 consecutive days. On the business side, the Essential plan is reported to carry no minimum balance and a monthly subscription after an introductory period, which suits freelancers and small companies that want invoicing tools in the same app.
Emirates Islamic: zero balance with a salary
The Emirates Islamic current account advertises no minimum balance charges when your salary is transferred, with a minimum salary of AED 5,000. Without that transfer, the bank asks for a minimum balance of AED 3,000. The account comes with a free debit card and can be held in several currencies, including USD, GBP and EUR, although debit cards and cheque books are not issued on the foreign currency versions.
If your salary already goes to an Emirates Islamic account, this is an easy yes. If you are between jobs or paid irregularly, it is a poor match.
Emirates NBD and Liv: choose the right door
Emirates NBD says on its accounts page that minimum balance requirements depend on the account type and your relationship with the bank. That is the polite way of saying the branch accounts vary. Its digital brand Liv is reported to have no salary requirement, with a monthly spend, a credit card or a balance available as ways to avoid fees. If you choose Emirates NBD, our walkthrough on how to check your Emirates NBD balance covers the app, the online portal and the other routes.
FAB iSave and the FAB current accounts
FAB iSave is a savings account, not a current account, but it fits the brief closely. There is no minimum balance, no limit on the number of withdrawals, and if you already bank with FAB you can open it instantly in the mobile app or online banking. It is available in dirhams only. The rate is promotional and moves, so look at the current figure before you move money across.
The picture is different on the current account side. One comparison lists FAB One as needing a AED 10,000 salary or a AED 10,000 deposit, which is no help to someone chasing a low threshold. Once your FAB card is in your wallet, our guide to checking your FAB balance shows the quick ways to do it.
HSBC, Al Hilal and SIB
One comparison site reports that the HSBC Flexi Account needs neither a salary nor a balance under any condition. HSBC’s eSaver is a fully digital savings account with a zero minimum, although the interest tiers are modest for smaller balances.
Al Hilal and SIB Digital are the two Islamic options where sources disagree. One review quotes Al Hilal’s key facts statement as stating no minimum balance requirement. Another says you avoid the fee only by holding AED 3,000, an active credit card or a finance product. SIB Digital is marketed as zero balance and opens in the app with an Emirates ID, yet one listing mentions a AED 5,000 salary. Two sources and two answers is exactly why you ask the bank, and read the key facts statement, before you apply.
Savings accounts that ask for very little
If you are looking to set money aside rather than spend it, a few more names are worth a look. CBD’s GreenGrowth account is described as zero balance with no maintenance fees. Standard Chartered’s XtraSaver has no monthly balance requirement, although it starts with a AED 3,000 opening deposit. Mashreq’s Easy Saver carries no monthly minimum or fee, but it is meant for people who already hold a Mashreq account. These are useful side accounts. They are not built to receive a salary.
Which Account Fits Your Situation
| Your situation | Sensible place to start |
| New arrival waiting for the first salary | ruya, or a digital account that opens in the app with UAE PASS |
| Freelancer with uneven income | ruya for personal use. Wio Business Essential for client payments and invoices |
| Salaried at AED 5,000 or more | Mashreq NEO or Emirates Islamic, depending on whether you want conventional or Islamic |
| Prefer Islamic banking | ruya, Emirates Islamic, Al Hilal or SIB Digital. Check each condition first |
| Want to save, not spend | FAB iSave, CBD GreenGrowth or Standard Chartered XtraSaver as a side account |
| Send money home every month | Compare remittance fees and exchange rates before choosing, whatever the balance rule says |
If you send money abroad regularly, the exchange rate matters more than the balance rule. Our page on foreign currency exchange rates in Dubai explains how rates and margins work so you can judge what a bank is really charging you.
Costs to Check Beyond the Minimum Balance
A zero balance label deals with one fee. It says nothing about the others. Before you commit, run through this short list:
- Card and foreign currency charges. Some accounts add a margin whenever you spend in another currency.
- Cash machine fees. Withdrawals outside the bank’s own network can cost extra.
- Transfer and remittance fees. SWIFT transfers can cost anything from a few dirhams to well over AED 50 each, depending on the bank.
- Plan or subscription fees. Common with digital banks, and easy to miss if you focus on the balance rule alone.
- Dormancy rules. An account left empty and unused can be blocked or closed, as Wio’s key facts statement makes clear.
Every bank publishes a schedule of charges. It is dull reading, but ten minutes with it can save you a surprise deduction.
How to Open a Zero Balance Account Online
Most digital accounts follow a similar path. The steps below apply to the majority of the banks mentioned here.
- Check that your Emirates ID is valid and that you can sign in to UAE PASS. Both speed things up considerably.
- Read the bank’s key facts statement for the exact account you want. Look for the line about minimum balance and the line about fees.
- Download the bank’s app and start the application. Have your passport and residence visa details close at hand.
- Complete the identity check, which usually means a selfie and a scan of your Emirates ID.
- Activate your debit card, set up transaction alerts and note down your IBAN.
- If you are employed, send your HR team the IBAN so your salary can arrive through WPS.
Freelancers and business owners should keep a trade licence or freelance permit ready as well. The Central Bank of the UAE, which you can read about on Wikipedia, licenses the banks in this guide, so the same identity and anti-money-laundering checks apply to all of them.
Mistakes People Make With Zero Balance Accounts
- Assuming “no minimum balance” also means no salary requirement.
- Skipping the key facts statement and trusting a single blog post, including this one.
- Leaving an account empty for months and letting the bank block it.
- Ignoring plan fees because the marketing headline says zero.
- Moving your salary before checking how long the bank takes to credit it.
- Forgetting that a promotional rate can drop once the offer period ends.
Where to Apply: Official Pages
Always start from the bank itself. These pages are the ones to check before you apply:
- ruya: ruyabank.ae current account page
- Emirates Islamic: current account page
- Mashreq NEO: NEO current account page
- FAB: iSave account page
- HSBC: eSaver account page
- Wio: personal key facts statement
Final Thoughts
A no minimum balance account is worth having, but only if you know what kind you are getting. If you want zero conditions, ruya is the plainest option on this list. If your salary is steady, Mashreq NEO and Emirates Islamic give you room to breathe. If you are self-employed, a digital business account keeps client money organised without a heavy balance rule. And if you simply want to save, an account such as FAB iSave can sit quietly beside your everyday one.
Whichever you pick, spend five minutes on the key facts statement, keep some activity going, and put a reminder in your calendar to recheck the terms once or twice a year. Banks change their rules. Your habits should change with them.
This guide is for general information only and is not financial advice. Account terms, fees and eligibility change often, so confirm every detail with the bank before you apply.
Frequently Asked Questions
Is there really a UAE bank account with no minimum balance?
Yes. ruya states on its current account page that no minimum deposit or minimum balance is required. Many other banks waive the minimum only when you meet a condition, so the wording matters.
Do I need to transfer my salary?
Not always. ruya does not ask for one. Emirates Islamic waives its minimum balance when a salary of AED 5,000 or more is transferred, and Mashreq NEO accepts either that salary or a AED 3,000 monthly average balance, as its key facts statement shows.
Can freelancers open a no minimum balance account?
Often, yes. Digital banks tend to be more flexible than traditional ones. Freelancers may prefer a business plan such as Wio Business Essential for client payments. Our guide to the best banks in Dubai for expats also notes which banks are friendlier to self-employed applicants.
Are there other fees even when there is no minimum balance?
Yes. Plan fees, cash machine charges, transfer fees and currency margins can all apply. Read the schedule of charges and check how exchange rates in Dubai work before you send money abroad.
Can I open an account without an Emirates ID?
For most resident accounts, a valid Emirates ID is the starting point, and digital banks often pair it with UAE PASS. Non-resident options exist but are limited and usually come with higher thresholds.
Is a savings account with no minimum balance the same as a current account?
No. A savings account such as FAB iSave is designed to hold money and pay a return. A current account is built for daily spending and salary credits. Many people keep one of each.
What happens if my account sits empty?
It depends on the bank. Wio’s key facts statement says it may block or close an account that carries zero balance with no activity, or stays below the minimum, for 90 consecutive days. Keep a small amount moving through the account.
How do I check my balance once the account is open?
Your bank’s app is the quickest route. If you chose a large bank, our guides on how to check your Emirates NBD balance and how to check your FAB balance cover the main options.
Who regulates these banks?
The Central Bank of the UAE licenses and supervises banks operating in the country. Its Wikipedia entry gives a useful overview of its role.
Related Posts
- Best Banks in Dubai for Expats: The Complete Guide
- Foreign Currency Exchange Rates in Dubai, UAE
- Emirates NBD Balance Check: All Methods Explained for UAE Residents
- FAB Balance Check UAE: The Complete Guide to Checking Your Salary Card Balance
- How Much Do Movers and Packers Cost in Dubai
- Dubai Zip Code and Postal Code: Everything You Actually Need to Know